Payment Automation: How to Automate Invoices, Payables, Receivables and Reconciliation
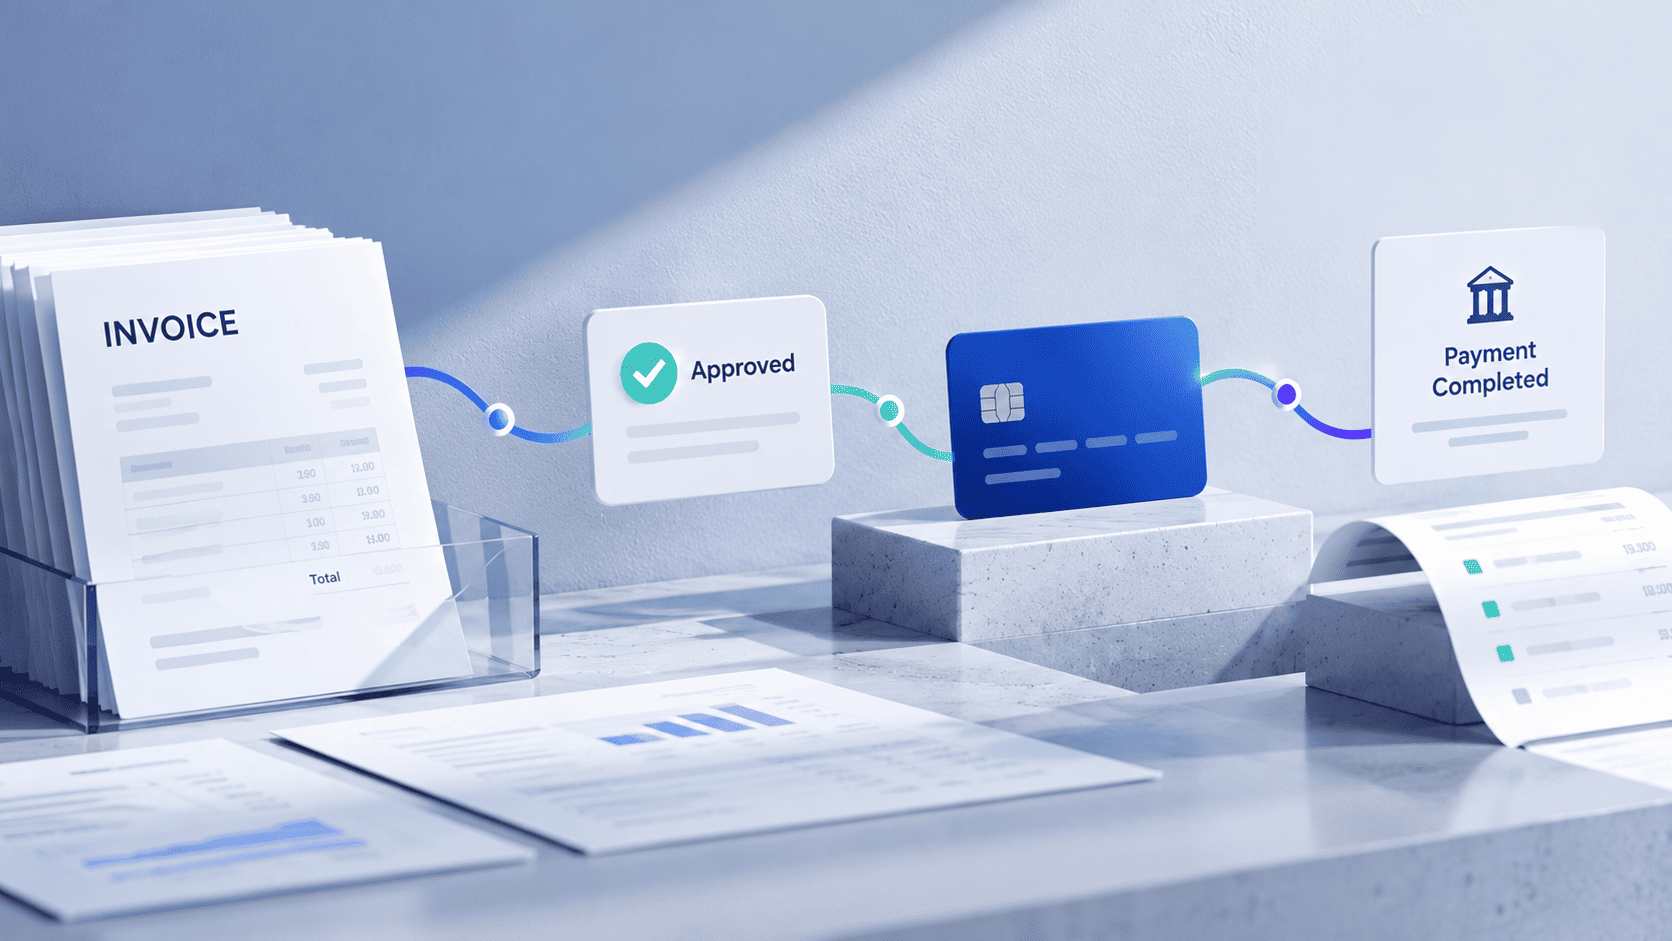
A supplier sends an invoice by email. An employee downloads the PDF, checks the amount, looks for a purchase order, requests approval and enters the details into accounting software. After payment, someone still needs to match the bank transaction to the invoice and update its status.
Repeat this process hundreds of times each month, and finance administration becomes a significant operational expense. Documents arrive through different channels, approvals sit in inboxes, payment references go missing, and employees spend hours resolving discrepancies.
Payment automation connects these activities into a coordinated workflow. It captures documents, validates information, routes approvals, prepares payment instructions, updates accounting records and matches transactions against outstanding balances.
This guide explains how to automate the payment cycle, calculate the cost of manual processing, choose appropriate technology and introduce automation while maintaining financial controls.
Key Takeaways
- Payment automation connects invoice intake, approval, payment execution, accounting updates and reconciliation.
- Manual processing costs include staff time, corrections, follow-ups, late fees and delayed collections.
- Accounts payable automation manages supplier invoices and outgoing payments, while accounts receivable automation supports billing and collections.
- AI can interpret varied documents; explicit rules should control calculations, approval limits and payment release.
- A three-to-six-week pilot can measure processing time, exception rates and automation coverage before expansion.
What Is Payment Automation?
Payment automation uses software, integrations and workflow rules to manage repetitive financial activities. Depending on the business, the system may connect email, procurement tools, accounting software, banking services, payment processors and approval applications.
When a supplier sends an invoice, the workflow extracts and validates its data, checks for duplicates, matches the purchase order and routes the invoice for approval. Once approved, it prepares or submits the payment through an authorised integration.
Online payment acceptance solves a narrower problem: it enables a customer to pay electronically. Payment process automation coordinates the surrounding work, including billing, approvals, accounting entries, reminders and reconciliation.
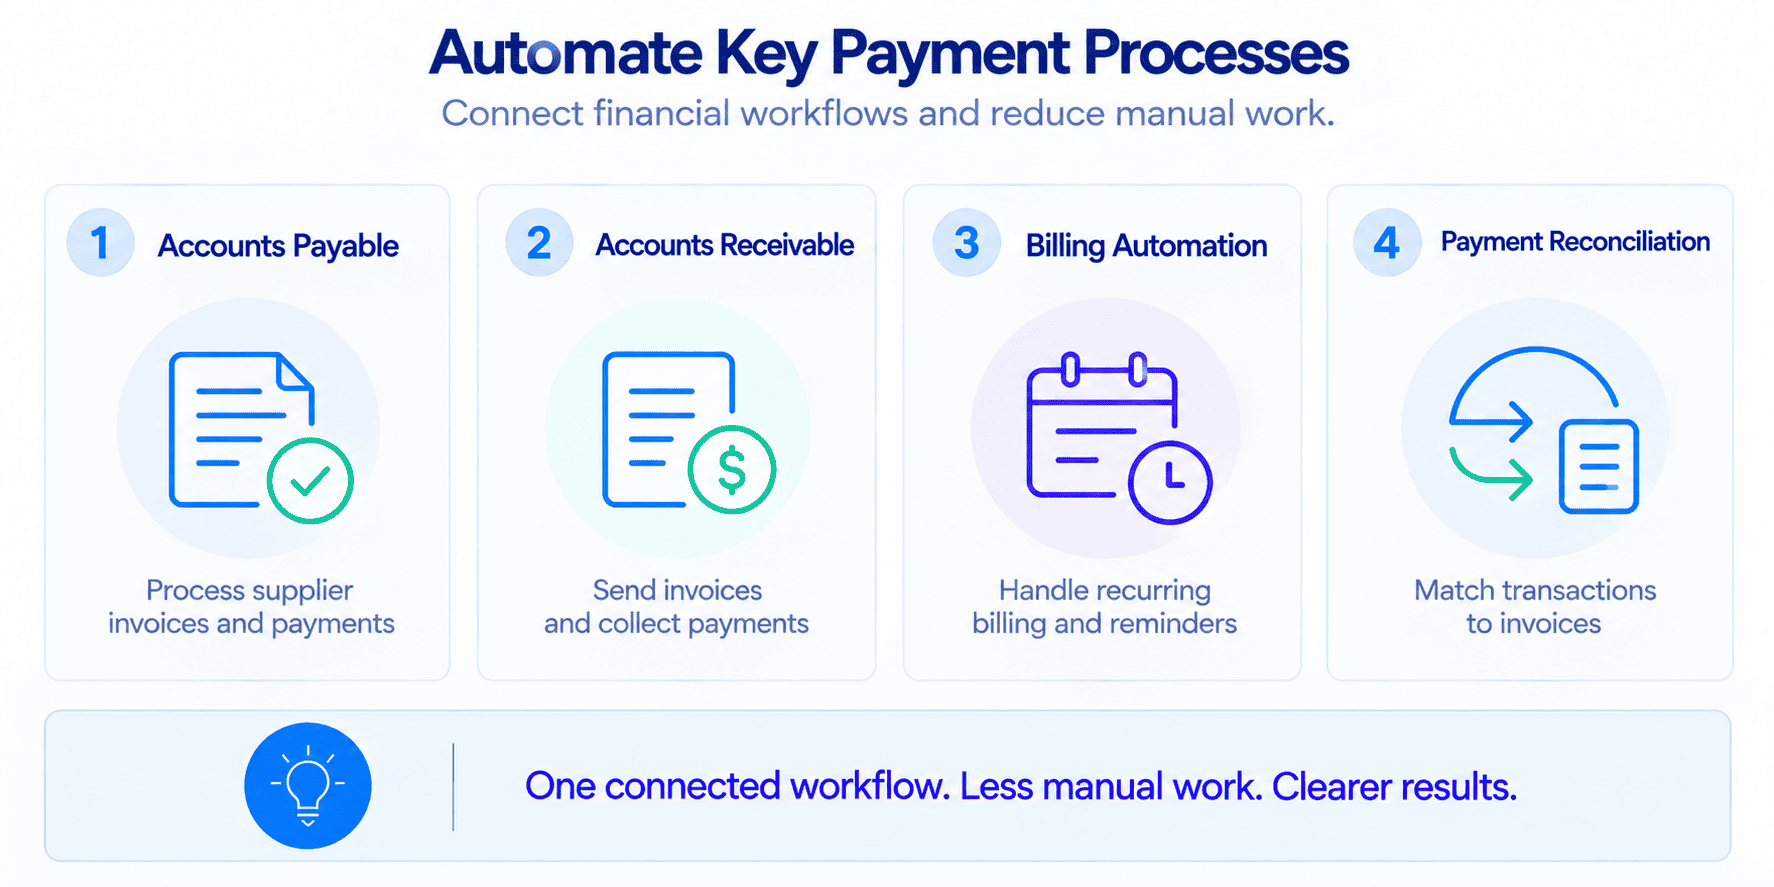
A complete solution usually combines four functions:
- Invoice processing automation: Captures documents, extracts fields, validates data and detects duplicates.
- Accounts payable automation: Manages supplier invoices, purchase-order matching, approvals and outgoing payments.
- Accounts receivable automation: Generates customer invoices, monitors due dates and supports collections.
- Payment reconciliation: Matches bank and processor transactions to invoices and accounting records.
For business-to-business operations, B2B payment automation is especially useful when financial information moves between procurement, finance, account management and external payment providers.
Where Manual Processes Lose Time and Money
Manual work looks inexpensive when each task is considered separately. The cost becomes clearer when employees repeatedly download documents, copy data, chase approvals and investigate discrepancies.
A distributor may receive invoices through multiple inboxes and portals, approve purchases by email and track due dates in spreadsheets. This fragments payment data across systems. Automation centralises transaction records, tracks approvals and flags missing purchase orders or overdue tasks.
How Much Does Manual Processing Cost?
Build the business case using your own transaction volume and labour costs.
Cost per invoice = (Processing minutes ÷ 60) × Fully loaded hourly cost + Additional correction cost
The fully loaded hourly cost includes salary, employer taxes, benefits and other relevant employment expenses. Correction costs cover time spent resolving missing documents, errors and supplier questions.
Suppose a company processes 600 invoices per month. Each invoice requires 12 minutes of initial work and two minutes of follow-up. The fully loaded labour cost is $30 per hour.
These illustrative figures exclude payment fees, late penalties and financing costs. Calculate payment administration separately if it includes beneficiary verification, bank submission, confirmation and ledger updates.
Cost per payment = Total payment-administration cost ÷ Number of payments processed
Then estimate potential savings. If automation reduces processing from 14 minutes to five minutes per invoice, the example company saves nine minutes per invoice. At 600 invoices monthly and $30 per hour, that represents a theoretical labour-cost reduction of $2,700 per month before implementation and maintenance costs. Use the Atomic Actions automation ROI and cost-benefit analysis guide to build a more complete investment model.
The Complete Payment Workflow
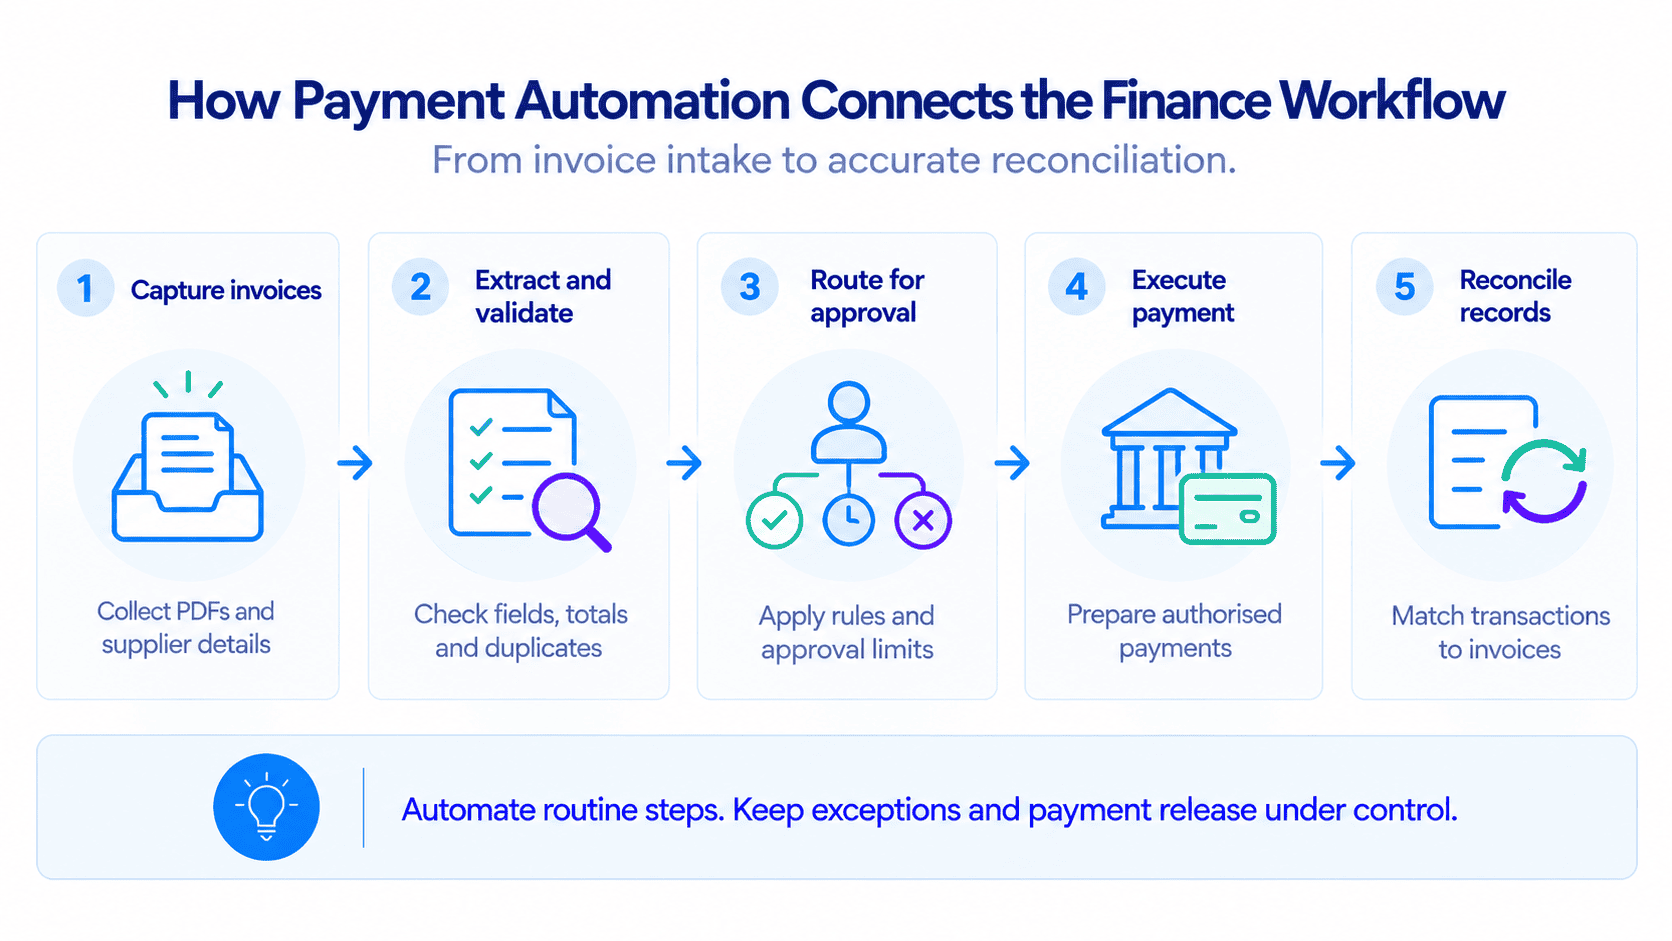
A reliable payment process automation system follows the transaction from the initial request to the final accounting entry.
The workflow must also define what happens when information is missing, an approval is overdue or a payment fails. A purchase order might use a different reference from the invoice, or a bank transaction might arrive before the invoice has been posted. The guide to workflow design and edge cases explains how to design reliable exception paths alongside the main process.
Accounts Payable Automation
Accounts payable automation manages the money a company owes suppliers. It reduces repetitive invoice handling and helps finance teams maintain consistent approval and payment records.
Capture and extract invoices
Invoices may arrive as PDF attachments, scans, electronic documents or portal downloads. An invoice automation workflow can monitor designated inboxes, accept uploads and preserve each original document.
OCR and AI-assisted extraction support automated invoice processing by identifying the supplier, invoice number, issue date, due date, currency, tax and total. The workflow then validates these fields against trusted business records.
Important checks include:
- Required fields are present and correctly formatted.
- Supplier details match an approved vendor record.
- Invoice numbers and amounts are checked for duplicates.
- Totals and taxes reconcile within permitted rules.
- Purchase orders and delivery evidence exist where required.
Explore Data Extraction & Recognition for document-processing capabilities.
Match and approve
Three-way matching compares an invoice with the purchase order and goods receipt. For services, the supporting evidence may be an approved timesheet or milestone confirmation.
Approval routes can depend on the amount, department, cost centre and budget owner. The workflow should record who approved the invoice and which version was reviewed. If the amount or beneficiary changes, the system should reassess whether the approval remains valid. The case study on automated invoice creation from PDF packing slips illustrates document extraction, validation and accounting integration.
Invoice Processing Automation and Duplicate Prevention
Invoice processing automation standardises documents arriving in different formats. A typical workflow receives the file, identifies its type, extracts fields, normalises data, validates the results and creates or updates the financial record. Effective invoice automation also standardises validation rules across document formats, helping finance teams process invoices consistently.
Reliable automated invoice processing requires duplicate detection because the same invoice may arrive through email and a supplier portal, while a corrected invoice may legitimately reuse an earlier reference. The same invoice might arrive through email and a supplier portal, while a corrected invoice may legitimately reuse an earlier reference.
Use several signals together: supplier ID, normalised invoice number, date, currency, amount and, where appropriate, a file hash. No single field should determine every case. For further guidance, see How Businesses Automate Data Entry with AI Parsing.
Accounts Receivable Automation
Accounts receivable automation manages customer invoices, collections and expected cash inflows. A workflow can generate an invoice when an order is confirmed, goods are delivered or a project milestone is approved. It records the due date and schedules reminders according to the company's payment terms. The lead-to-final-payment case study demonstrates how connected business processes can link customer activity with payment.
A practical reminder sequence includes:
- Before the due date: send the invoice and payment instructions.
- On the due date: confirm the outstanding amount.
- After the due date: follow the agreed collection schedule.
- When a dispute arises: assign an owner and pause inappropriate reminders.
- When payment arrives: update the invoice and stop collection messages.
Cash-flow forecasts can combine due dates, historical payment behaviour, customer terms and known disputes. Useful measures include overdue receivables, days sales outstanding (DSO) and the percentage of invoices paid on time. The business management system case study provides an example of connecting operational and financial workflows.
Payment Reconciliation
Payment reconciliation matches actual money movements to the invoices and accounting entries they are expected to settle. It helps identify outstanding balances, duplicate entries and transactions requiring investigation. A matching engine should start with reliable references and expand to less certain signals.
A customer might owe $2,000 but transfer $1,950 after deducting a credit. The workflow should identify the $50 difference and request evidence or approval instead of marking the balance as fully paid.
Unidentified funds should remain visible in a suspense or unapplied-cash workflow. Reconciliation should also account for refunds, chargebacks, failed transfers, reversals and settlement delays.
Payment Methods and Automation
Payment methods affect settlement timing, reference quality, fees and the data available for automated payment processing.
B2B payment automation should reflect the methods the company actually uses. A subscription business may prioritise card events and recurring billing, while a distributor may focus on bank transfers and supplier payments. International workflows also need explicit rules for exchange rates, bank charges and reporting-currency amounts.
Billing Automation and Recurring Payments
Billing automation generates invoices according to commercial agreements. It supports subscriptions, retainers, usage-based pricing and recurring service contracts. For businesses managing multiple invoice types, invoice automation can standardise document generation, approval and delivery across recurring and one-off transactions.
Billing rules should be versioned so that price changes, contract renewals and tax updates take effect on the correct date. For businesses connecting orders, billing and collections, see the case study on a connected lead-to-payment system.
Fraud Prevention and Financial Controls
Automation should enforce financial controls and protect against business email compromise, where attackers impersonate suppliers to change bank details. Extracting new details does not verify their legitimacy. Confirm changes through a trusted contact and require authorised approval.
Essential controls include:
- Separate invoice creation, approval and payment release where practical.
- Apply approval thresholds to higher-value transactions.
- Validate beneficiaries against approved vendor records.
- Check for duplicate invoices and payment instructions.
- Restrict user and integration permissions.
- Maintain audit logs and exception alerts.
- Keep high-risk payment release under authorised control.
AI can flag suspicious changes and summarise evidence. Explicit rules and authorised approvals should govern financial actions with significant consequences.
Integrating Accounting Systems
Payment automation depends on consistent financial data. Even correctly extracted invoice details can create problems if the workflow selects the wrong legal entity, tax code or accounting period. In B2B environments, connecting procurement, accounting and banking systems helps B2B payment automation maintain consistent transaction data from invoice approval through settlement.
Integrations should handle outages and retries without creating duplicate records. Idempotency ensures that processing the same event twice does not create two invoices or payments. A business management system for operations, finance and compliance illustrates how connected workflows can support financial operations. For a broader approach to connected business data, read Single Source of Truth Beyond ERP.
Choosing the Right Automation Level
For businesses with predictable invoice flows and straightforward approval rules, payment automation software built with Make or n8n may be sufficient. It can connect document extraction, accounting software and notifications without introducing a new interface.
AI agents add value when the system must interpret varied invoice layouts, read remittance advice or summarise discrepancies. They should operate within defined permissions and confidence thresholds.
A custom application becomes useful when finance staff need one place to review invoices, approve transactions, investigate exceptions and monitor payment statuses. Explore Robotic Process Automation for additional implementation approaches.
A custom CRM for payroll, contracts and compliance offers another example of centralising business records and workflows. Also, Business Optimization & Analytics can help identify bottlenecks and measure the operational impact of automation.
Where AI Helps and Where Rules Are Better
This combination supports automated payment processing while keeping calculations, permissions and high-risk financial decisions auditable.
Metrics to Measure
Establish a baseline before implementation and use consistent definitions throughout the pilot.
Interpret DSO and DPO in the context of payment terms, seasonality and accounting policies. Review results weekly and segment exceptions by supplier, document type and amount.
Implementing Payment Automation in Three to Six Weeks
- Week 1: Map the process. Choose one workflow, document its steps and systems, identify its owner and measure processing time, volume and correction rates.
- Week 2: Design the rules. Define required fields, statuses, approval limits, exception routes and the system of record. Prepare test documents, including duplicates and mismatched invoices.
- Weeks 3–4: Build and test. Connect the relevant tools, implement validation and routing, and verify retries, permissions and audit logs. Keep payment release under existing authorised controls.
- Weeks 5–6: Run a controlled pilot. Process a limited set of real transactions and compare results with the baseline.
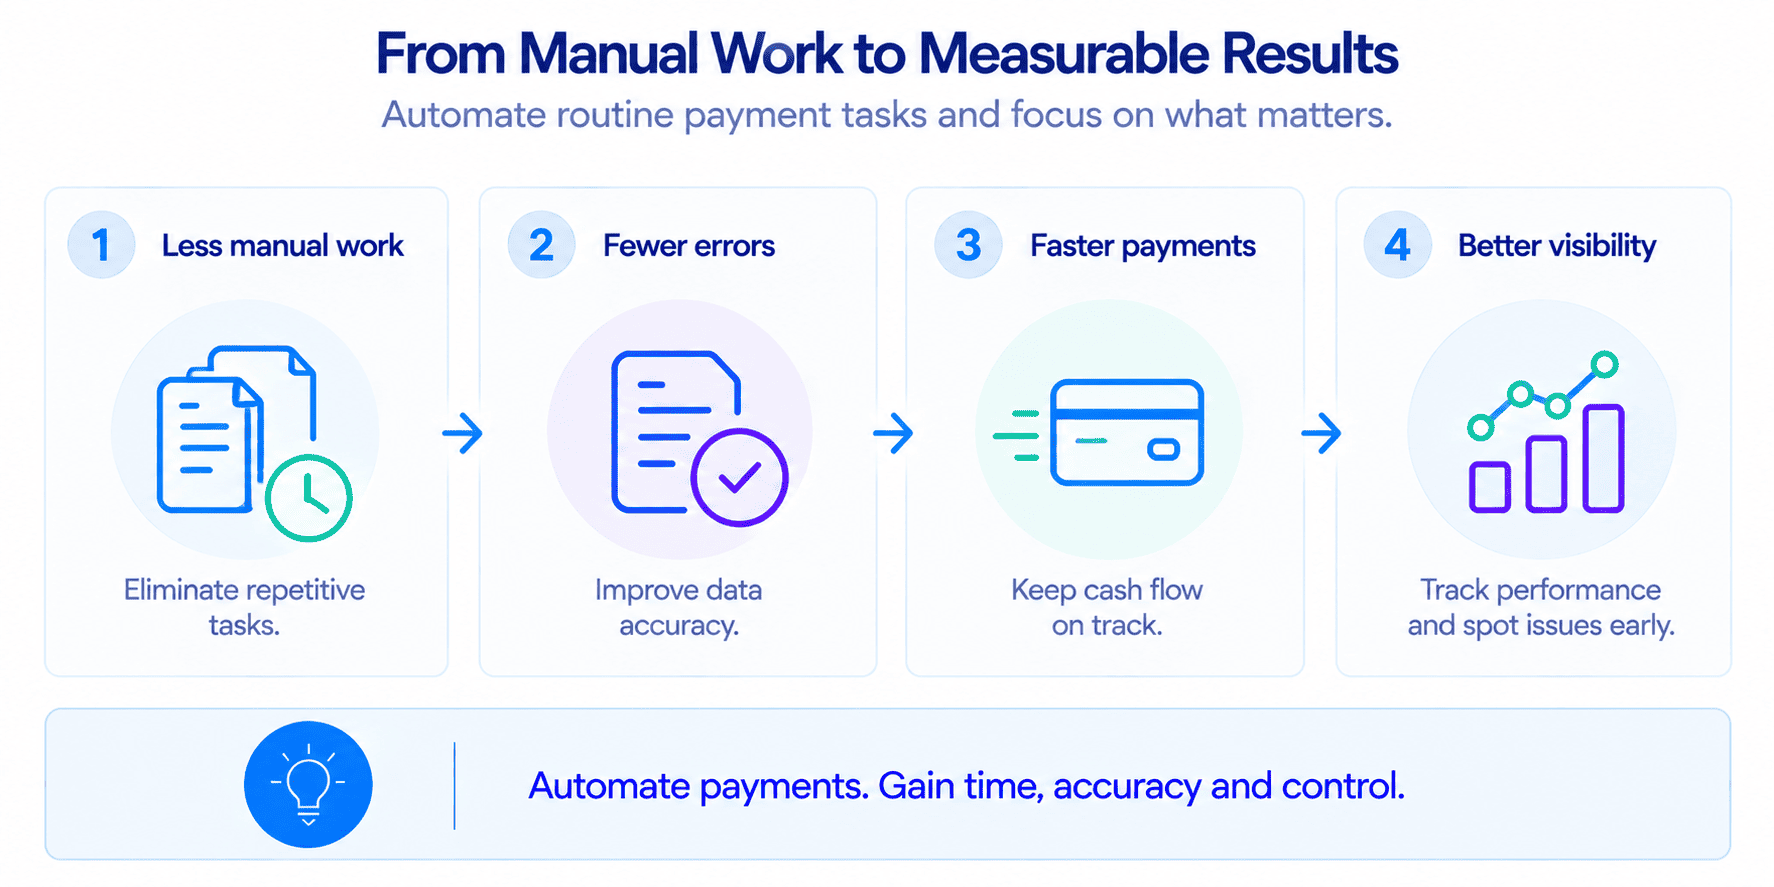
The pilot should demonstrate reduced processing time, reliable records, correct exception handling, stable integrations and a credible estimate of operating costs. Before implementation, review Operational Discovery Before Implementation. Expanding a stable workflow is easier when responsibilities and exception paths are clear from the start.
Common Implementation Mistakes
- Automating an unclear process. Define responsibilities and approval rules before building the workflow.
- Ignoring exceptions. Missing purchase orders, partial payments, refunds and disputes need documented resolution paths.
- Giving integrations excessive permissions. Restrict access to the data and actions required for each task.
- Treating extracted data as verified data. Validate fields against trusted records and route uncertain cases for review.
- Skipping monitoring. Add alerts, retry limits and an operational owner for failed integrations.
- Measuring activity instead of outcomes. Track processing costs, cycle times, exception rates and reconciliation performance.
Unresolved process gaps create operational debt that grows as transaction volumes increase. Addressing these issues early helps businesses scale payment workflows without adding unnecessary manual work. Learn more about operational debt and business growth.
Conclusion
Effective payment automation starts with one measurable bottleneck. Invoice capture, data extraction or payment matching can provide a practical first step, creating a foundation for connected approvals, billing, receivables and reconciliation.
The right technology depends on the workflow. Make or n8n can connect existing services, AI-assisted extraction can handle variable documents, and a custom application can provide a unified workspace when permissions and exceptions become more complex.
Atomic Actions helps businesses connect systems, automate document-heavy workflows and build custom operational tools. Contact us to identify an approach suited to your operations.
FAQ
What is payment automation?
Payment automation uses software and integrations to manage invoice capture, validation, approvals, payments, billing and reconciliation.
How is payment automation different from online payment processing?
Online payment processing enables electronic transactions. Payment automation connects those transactions to invoices, approvals, accounting records and reconciliation.
How much does payment automation software cost?
The cost of payment automation software depends on transaction volume, integrations, document complexity, security requirements and whether the solution uses existing tools or a custom application. Compare implementation and maintenance costs with measured savings.
Can payment automation work with existing accounting software?
Yes, when the accounting platform supports suitable integrations, APIs or reliable import methods. Supplier records, statuses, tax codes and accounting periods must be mapped correctly.
Can AI process invoices without human review?
Many routine invoices can be processed automatically after validation. Uncertain fields, missing orders, unusual totals and suspicious bank-detail changes should be reviewed according to risk policy.
How does payment reconciliation handle partial payments?
The system allocates the received amount to the invoice, records the settled portion and keeps the remaining balance open. Combined payments can be allocated across multiple invoices when the evidence supports the match.
How long does implementation take?
A focused pilot may take three to six weeks when the scope is clear and the required systems are accessible. Complex integrations and security reviews can extend the timeline.
Which payment process should a business automate first?
Start with a high-volume, repetitive task that has measurable delays and reliable source data. Invoice capture or payment reconciliation is often a practical starting point.